Financial Report FAQs
Categories:Tips and Guidance, Finance
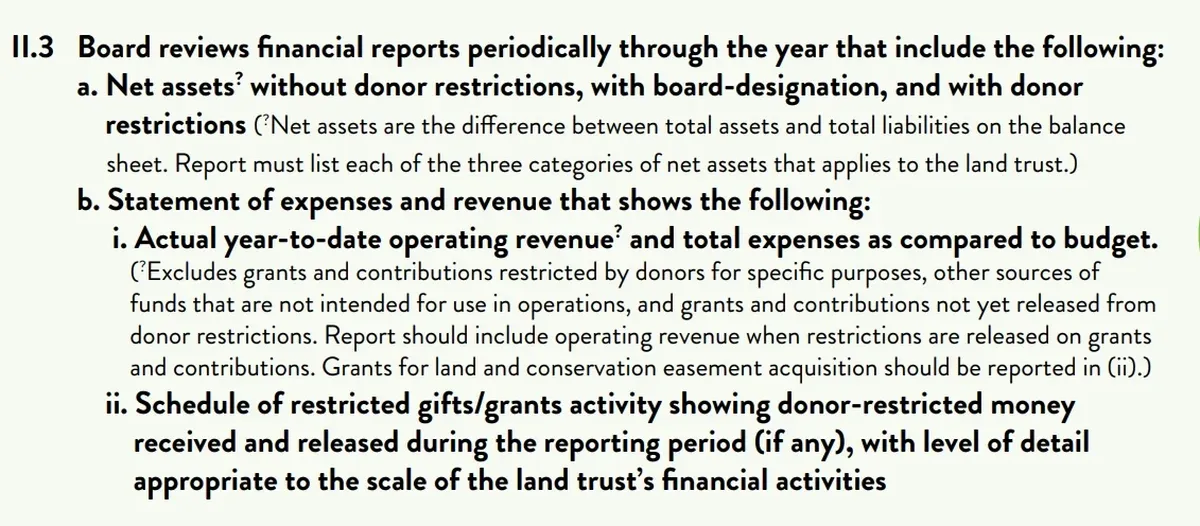
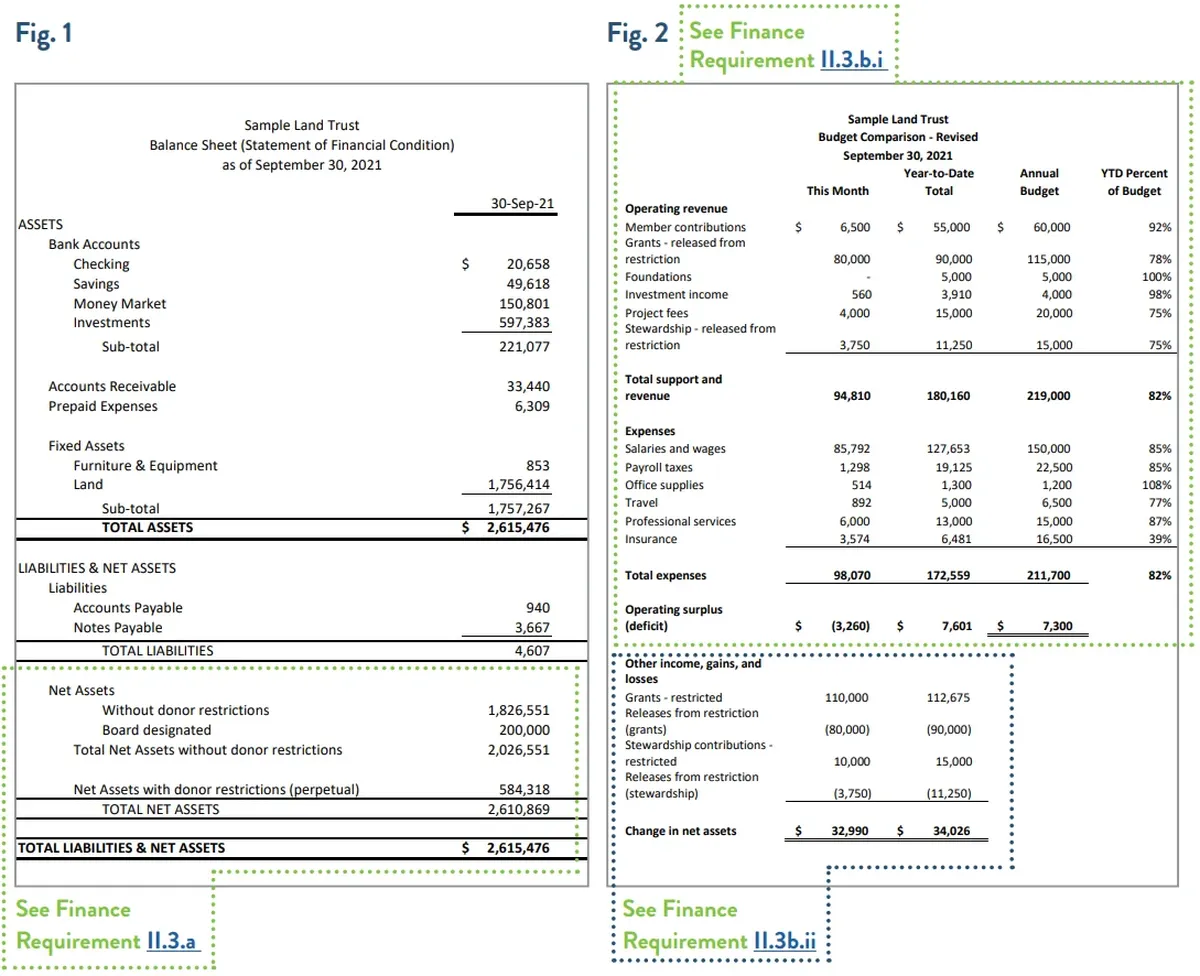
Detailed financial reports help board members meet their fiduciary obligations. The contents described in the requirements allow a board to a) see how financially strong the land trust is and if there are there limitations on what the land trust can do with its resources and b) track the land trust's current performance against the budget and help it understand if a portion of the revenue for the reporting period is not available to cover general operating expenses because it is restricted for land or easement acquisitions or for other purposes.
Here are answers to questions that the Commission has been hearing from land trusts. While it is not accounting advice, the answers give insight into what accreditation reviewers look for when considering your application.
Q: How much detail do we need to provide on the financial reports? Can we show the board 'rolled-up' information or do we have to show each account line item? For example, the total net assets without donor restrictions or board designated vs. the three funds that make up the board designated moneys?
A: Reports should allow the board to easily see what the total net assets are and what portion is actually available. You can show rolled-up information, it does not have to contain the name or purpose of each fund.
Q: Does the land trust have to maintain different bank accounts for donor-restricted funds?
A: No, separate bank accounts are not required for restricted money vs. those without restrictions. Rather, land trusts must have an accounting system that tracks when donor-restricted funds have been received and when the funds have been released from restriction so that it can report on them accordingly.
Q: On the budget comparison report, what happens if we have not released funds during the reporting period?
A: The reports only need to show what happens during the specific reporting period. By using the phrase "if any," the requirement signals that this information is needed when restricted grants/gifts are received and/or released from restriction.
Q: Why do we need to show the board reports with both the balance sheet and the budget comparison?
A: These reports provide different information to the board and are an important part of the board providing oversight of the land trust's finances. The balance sheet shows how your land trust is doing overall – your assets, what you owe and importantly, what portion of your net assets is reserved for other purposes (by being board designated or donor restricted). The budget comparison report shows how your organization is doing as it relates to revenue and expenses so the board can anticipate if there will be a deficit and how well the land trust is performing against the budget that was set at the beginning of the fiscal year.
Q: Are both balance sheet and budget comparison sheets expected to be given to the Board at every meeting?
A: The requirement is that the reports be given periodically; so, it is not enough to only give the reports once a year as part of your annual external financial evaluation. Most land trusts provide both reports to board members before each meeting, others may provide the information on net assets (usually a balance sheet or statement of financial position) less often. Whatever way your land trust presents the information, it is important for your board to have financial information throughout the year so it can make sound financial decisions.
Q: Do monthly budgeted distributions from endowments need to be listed, when they are released into operations, on the budget comparison report in the income, gains, and losses section?
A: Yes, you should show released endowment funds as income coming into your organization. Even though it's budgeted, you want your report to reflect that it is part of your operating revenue.
Q: If our board has a finance committee, is it enough for them to be the ones to review the finance reports periodically or does our entire board have to review the reports?
A: Your entire board has fiduciary responsibility and should be given the reports on a periodic basis. A finance committee might review the reports in advance of the full board or more frequently than the full board, but review by only the finance committee is not sufficient to meet the requirement.
Q: What happens if you're in process or about ready to submit your application and you realize that you now have a different understanding or more clarity that you didn't have when you looked at an older version of the Requirements Manual?
A: The accreditation process allows for an opportunity for land trusts to provide additional information or take corrective action. We often see that the initial information that comes in with the application might not fully meet the requirements – whether it's a policy or the financial reports – so land trusts are given time to take corrective action and convey the updated information back to the Commission.